Storm & Hail Damage Roofing in Oklahoma City
Storm and hail damage should be documented, not assumed.
Start with the condition of your property before you file a claim or commit to repairs.
A storm can leave obvious damage, subtle concerns, or no repairable damage at all. A missing shingle, dented vent, or damaged gutter deserves attention. But one visible condition does not automatically mean the entire roof needs to be replaced.
Our Free, No-Obligation Forensic Roof Assessment (FRA) documents visible roofing and exterior conditions, provides photographic evidence and written observations, and helps you understand your options.
If damage is present, we'll show you. If it isn't, we'll tell you that too.
No pressure. No claim pitch. Just facts.


Licensed by the Oklahoma Construction Industries Board
(CIB REG: 80007114)
Fully Insured
Veteran Operated
7-Year Workmanship Warranty on Qualifying Complete Roof Installations
Backed by Decades of Roofing and Construction Experience
Clear roofing help after hail, wind, or severe weather.
8:12 Roofing & Exteriors helps Oklahoma City homeowners evaluate visible roofing and exterior conditions after a storm.
We can help you:
Understand what happened to the property.
Document visible roofing and exterior concerns.
Consider whether an insurance claim deserves further discussion.
Coordinate the assessment with an adjuster visit when appropriate.
Understand the roofing and construction scope.
Compare repair and replacement options.
Evaluate related gutters, siding, windows, and exterior concerns.
Complete the work you approve.
Maintain important project records.
We do not begin by assuming you need a claim or a new roof. We begin with the facts.
The storm has passed. Start with safety.
Severe weather can leave loose materials, damaged trees, broken glass, exposed electrical hazards, unstable ceilings, and unsafe roof conditions.
Recommended Steps:
Make sure people and pets are safe.
Stay away from downed power lines and damaged electrical areas.
Do not climb onto the roof.
Keep people away from sagging ceilings or unstable structures.
Photograph visible damage from the ground when it is safe.
Move undamaged belongings away from active water entry when practical.
Use containers to collect water when it is safe to do so.
Keep receipts for approved emergency or temporary work.
Request a professional assessment of the roof and exterior.
If there is a fire, a gas leak, a downed power line, a tree affecting the structure, a partially collapsed roof, or an immediate threat to people, contact the appropriate emergency service or utility before contacting a roofing company.
Reasonable temporary steps may help reduce additional damage, but homeowners should not place themselves at risk. Do not make major permanent repairs before the conditions have been properly documented and the insurance process has been considered.
A storm report is a reason to look. It is not a roof diagnosis.
Weather reports, neighborhood activity, dented vehicles, damaged trees, and nearby roof replacements can provide useful context. They do not prove that your roof needs repair or replacement. The recommendation should be based on the property itself.
Useful Context May Include: Storm date and approximate time, reported hail or wind in the area, damaged trees or fencing, dents in exterior metals, torn window screens, missing or displaced shingles, water intrusion, nearby storm reports, and photographs or video from the homeowner.
Weather information can help establish that a storm occurred. A physical assessment helps establish what happened to your property.
Proof comes from the property, not the sales pitch.
Storm-related concerns are not always visible from the ground.
Some storm-related conditions are obvious. Others are small, concealed, or difficult for a homeowner to evaluate safely. Possible signs that deserve professional attention may include:
Roofing
Missing or displaced shingles, lifted or creased shingles, broken or cracked roofing materials, damage around ridges and roof edges, disturbed flashing, damaged vents or penetrations, debris impact, water entry, new ceiling stains, and loose roof components.
Gutters and Exterior Metals
Dents, scrapes, distortion, loose sections, damaged downspouts, displaced flashing, and damaged vent covers.
Siding, Windows, and Exterior Components
Cracked or displaced siding, damaged screens, broken glass, dented metals, loose trim, impact marks, and damaged exterior fixtures.
Trees and Property
Fallen limbs, tree contact with the roof, damaged fencing, debris on the roof, and impacted outdoor equipment.
Important Clarification: One visible condition does not automatically prove the cause of the condition, the full extent of the damage, whether the roof can be repaired, whether replacement is appropriate, or whether insurance coverage applies.
See the evidence. Understand what it means. Then decide what comes next.
Hail and wind affect roofing systems differently.
Hail-Related Concerns
Hail may affect roofing materials, ridge and hip materials, roof vents, flashing, gutters and downspouts, siding, window screens, exterior metals, and other exposed components. Dents in a vent, gutter, or other soft metal may provide useful storm context. They do not automatically establish that the roof covering requires replacement.
Wind-Related Concerns
Wind may lift or displace shingles, crease roofing materials, remove shingles or ridge caps, disturb flashing, damage vents or accessories, move debris across the roof, cause tree or limb impact, and damage gutters, siding, or trim.
Water Entry
Some storm conditions cause immediate leakage. Others may not produce an obvious interior symptom right away. The property should be evaluated based on visible evidence, roof-system performance, repairability, and the complete property context.
No leak does not automatically mean no concern. A dent does not automatically mean a new roof.
Start with facts, not assumptions.
A Free, No-Obligation Forensic Roof Assessment provides a documented look at visible roofing and exterior conditions. The assessment can include the roofing and exterior areas the homeowner wants evaluated.
What the Homeowner Receives:
Photographic documentation.
Measurements when applicable.
Marked areas of concern.
Clear written observations.
A review of the findings.
An explanation of reasonable next steps.
Written observations are always delivered.
If there is damage, we'll show you. If there isn't, we'll tell you that too.
We Start With the Truth.
Do you even need to file an insurance claim?
Fair question. You might not.
A claim decision may depend on the visible condition of the property, the likely repair scope, the estimated cost of the work, the homeowner's deductible, the insurance policy, the reported cause and date of loss, the homeowner's circumstances, and guidance from the insurance agent or carrier.
8:12 does not determine insurance coverage. Our role is to provide clear roofing and construction information so the homeowner can make a better-informed decision.
A Claim May Deserve Consideration When:
Storm-related damage appears significant, multiple roofing or exterior areas are affected, repair or replacement costs may materially exceed the deductible, the homeowner wants the carrier to inspect a possible covered loss, or the property may require broader restoration.
Direct Repair May Deserve Consideration When:
The concern is limited, a focused repair is responsible, the cost is near or below the deductible, the homeowner does not want to pursue a claim, and the surrounding roof remains serviceable.
These are general considerations, not insurance or legal advice.
We're not here to push a claim. We're here to give you a straight answer.
What to Expect
Request Your Free Forensic Roof Assessment
Tell us what happened, where the property is located, and whether an adjuster visit has already been scheduled.
We Coordinate the Assessment
We confirm timing, property access, gates, pets, areas of concern, exterior components to evaluate, adjuster information when applicable, and safety conditions. (You do not need to be present when safe, authorized access has been arranged.)
We Inspect and Document the Property
A typical assessment takes about one hour. The property's size, design, condition, and adjuster collaboration may increase the time required.
We Deliver Written Observations
The homeowner receives the assessment documentation and written observations.
We Review the Findings
We explain what we observed, what appears storm-related, what may require repair, what may require replacement, what does not appear to require immediate work, and what we could not confirm.
You Decide Whether to File a Claim
The decision belongs to the homeowner.
When scheduling allows, we can meet the adjuster so visible roofing and exterior conditions can be reviewed at the property.
We Explain the Construction Path
After the carrier responds, we help explain the roofing and construction scope and the available repair or replacement options.
We document. We explain. We guide.
When possible, it helps to look at the same property at the same time.
If the homeowner files a claim, the insurance carrier may assign an adjuster to inspect the property. When scheduling allows, 8:12 can coordinate the Forensic Roof Assessment around that visit.
During the visit, 8:12 may point out visible roofing and exterior conditions, provide photographs or measurements, answer roofing and construction questions, identify components being evaluated, explain repairability concerns, discuss applicable construction methods, and document what was reviewed.
The homeowner is the policyholder. The carrier's adjuster evaluates the claim for the insurance company. 8:12 is the roofing and construction contractor. 8:12 does not determine coverage, negotiate the insurance settlement, or act as a public adjuster.
Same property. Same visible conditions. Clearer construction conversation.
The insurance estimate and the construction scope are connected, but they are not the same thing.
After the adjuster visit, the carrier may provide an estimate describing the work it evaluated. That estimate is not automatically the final construction plan.
8:12 may review the roofing and construction scope for items such as measurements, roofing materials, tear-off requirements, underlayment, water-protection materials, flashing, ventilation, roof accessories, gutters, decking considerations, applicable codes, manufacturer instructions, and required construction steps.
When Additional Information Is Needed
When documented construction needs differ from the carrier estimate, 8:12 may provide relevant construction information such as photographs, measurements, product information, code information, manufacturer requirements, scope details, and invoices.
Important Boundary: Providing construction documentation is not a promise that the carrier will approve or pay for an item. The carrier determines coverage.
The goal is not to create noise. The goal is to get the construction scope right.
Insurance language should not require a decoder ring.
Every insurance policy and claim can be different. These are general explanations, not a description of any homeowner's specific coverage.
Deductible
The portion of a covered loss the homeowner is responsible for under the policy. 8:12 does not waive, absorb, hide, or misrepresent the deductible.
Actual Cash Value (ACV)
Generally refers to the depreciated value of covered property at the time of the loss.
Replacement Cost Value (RCV)
Generally refers to the cost to repair or replace covered property according to the policy's terms and limits.
Depreciation
An amount reflecting age, condition, and other factors. Some policies may allow certain depreciation to be recovered after covered work is completed.
Adjuster
The person assigned to evaluate the claim for the insurance carrier.
Scope of Loss
The insurance company's scope of loss of the covered repair or replacement work. It is not automatically the contractor's final construction agreement.
Scope of Work
The detailed description of the construction work, materials, quantities, and project requirements.
Supplement
Additional construction documentation provided when the contractor identifies a documented construction need not reflected in the carrier's estimate. Coverage remains the carrier's decision.
The insurance policy controls. Homeowners should ask their insurance agent or carrier questions about coverage, deductibles, deadlines, endorsements, depreciation, exclusions, and claim decisions.
A storm does not come with one automatic answer.
After the property is assessed, the reasonable next step may be:
Focused Roof Repair
Repair may be appropriate when damage is isolated, surrounding materials remain serviceable, compatible materials are available, the condition can be addressed responsibly, and broader roof-system failure is not present.
Complete Roof Replacement
Replacement may deserve consideration when damage is widespread, multiple areas are affected, repair would leave substantial concerns unresolved, existing materials cannot be repaired responsibly, or the roof has broader age/condition concerns.
Exterior Repair or Replacement
A storm may affect gutters, downspouts, siding, windows, screens, exterior metals, and trim without requiring a complete roof replacement.
Monitoring or No Immediate Work
The assessment may not reveal work requiring immediate action.
If work is needed, we'll show you why. If it isn't, we'll tell you that too.
Explore 8:12's Easy Payment Option
Insurance may not cover every repair, upgrade, exterior component, or project choice. Explore payment options for qualified roofing and exterior projects while keeping control of your budget and available cash.
After the storm, choose the contractor as carefully as the roof.
Severe weather can bring a sudden wave of signs, door knocks, promises, and pressure. A trustworthy contractor should be easy to verify and willing to slow the conversation down.
Homeowner Checklist
Look for a contractor who: Has current Oklahoma roofing registration, carries appropriate insurance, uses a verifiable company name, has a real local presence, provides a written scope, explains repair/replacement options, explains insurance boundaries, does not guarantee claim approval, does not offer to waive the deductible, does not pressure you to sign immediately, uses real project photographs, provides clear warranty language, and remains reachable after the work is complete.
Red Flags
Be cautious when someone: Appears after the storm with no verifiable local history, says every nearby roof is damaged, guarantees insurance approval, promises a free roof, offers to cover or hide the deductible, pressures you to sign before explaining the scope, wants control of the insurance proceeds, avoids written details, cannot explain their registration, or uses fear as the main sales tool.
A storm creates urgency. It should not erase your judgment.
How We ELEVATE the Standard
A storm may be chaotic. Our process should not be.
Service begins before a contract is signed. It begins with showing up prepared, documenting the property, explaining the findings, respecting the homeowner's decision, and staying accountable through whatever comes next.
E
Exceed Expectations
Do more than the minimum. Prepare well, finish strong, and make the customer experience clear and professional.
L
Light the Way
Share what you know. Help teammates improve, step in when needed, and lead by example.
E
Evolve Your Craft
Keep learning. Seek better tools, stronger methods, better information, and honest feedback. What worked yesterday should not stop us from improving tomorrow.
V
Value Safety
Protect the customer, the public, yourself, and the team. Speak up when something is unsafe.
A
Act With Integrity
Tell the truth, even when it is inconvenient. Be honest about the work, the price, what happened, and what can or cannot be done.
T
Take Communication Seriously
Communicate clearly and early. Keep customers and teammates informed without making them chase you for answers.
E
Embrace Extreme Ownership
Take responsibility for results. Bring solutions instead of excuses. When something goes wrong, own your part, help fix it, and follow through until the next step is clear.
You can expect clarity. You can expect professionalism. You can expect follow-through.
How We ELEVATE the Standard
A storm may be chaotic. Our process should not be.
Our core values aren't just words on a website. They're the standards we hold ourselves to every day.
At 8:12 Roofing & Exteriors, ELEVATE is the foundation of who we are and how we do business. Our core values guide the decisions we make, the way we treat people, and the quality of work we deliver. They're woven into how we operate, how we lead, how we measure success, and how we hold ourselves and each other accountable.
We recognize and celebrate those who live these values, and when we fall short, we own it, learn from it, and do better. Because a company's character isn't defined by what it promises when everything is going right. It's revealed by what it does when things get difficult.
Service Comes Standard. And that standard starts with us.
E
Exceed Expectations
Do more than the minimum. Prepare well, finish strong, and make the customer experience clear and professional.
L
Light the Way
Share what you know. Help teammates improve, step in when needed, and lead by example.
E
Evolve Your Craft
Keep learning. Seek better tools, stronger methods, better information, and honest feedback. What worked yesterday should not stop us from improving tomorrow.
V
Value Safety
Protect the customer, the public, yourself, and the team. Speak up when something is unsafe.
A
Act With Integrity
Tell the truth, even when it is inconvenient. Be honest about the work, the price, what happened, and what can or cannot be done.
T
Take Communication Seriously
Communicate clearly and early. Keep customers and teammates informed without making them chase you for answers.
E
Embrace Extreme Ownership
Take responsibility for results. Bring solutions instead of excuses. When something goes wrong, own your part, help fix it, and follow through until the next step is clear.
You can expect clarity. You can expect professionalism. You can expect follow-through.
The storm may pass. Your project records should remain.
Workmanship Warranty
Qualifying complete roof installations performed by 8:12 include a 7-Year Workmanship Warranty. Repair warranties may differ by repair scope and written agreement. Contact us for a comprehensive breakdown of what your warranty covers.
Manufacturer Warranties
Manufacturer warranties vary by product, roof system, installation requirements, registration requirements, coverage selected, and manufacturer terms.
Your Project Has a Home Here
Available project records may include your Forensic Roof Assessment, before/during/after photographs, approved scope of work, product selections, warranty information, permit records, carrier construction documents, and completion documents.
Those records may be useful later for warranty support, a future insurance question, a home sale, an appraisal, a mortgage-company request, or property documentation.
Local roofers. Lasting support.
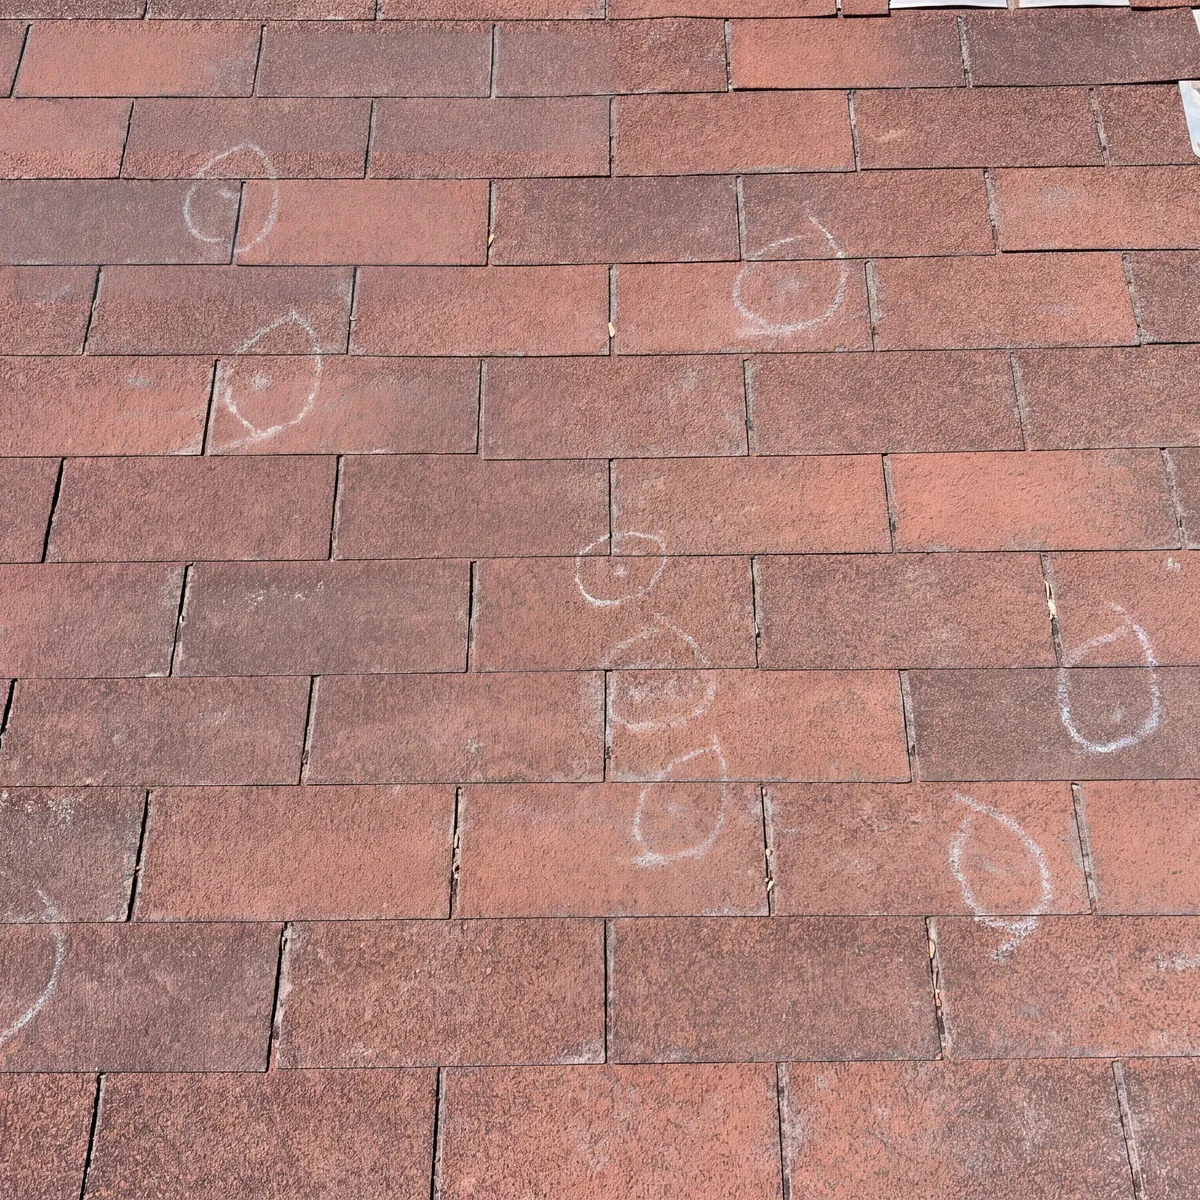
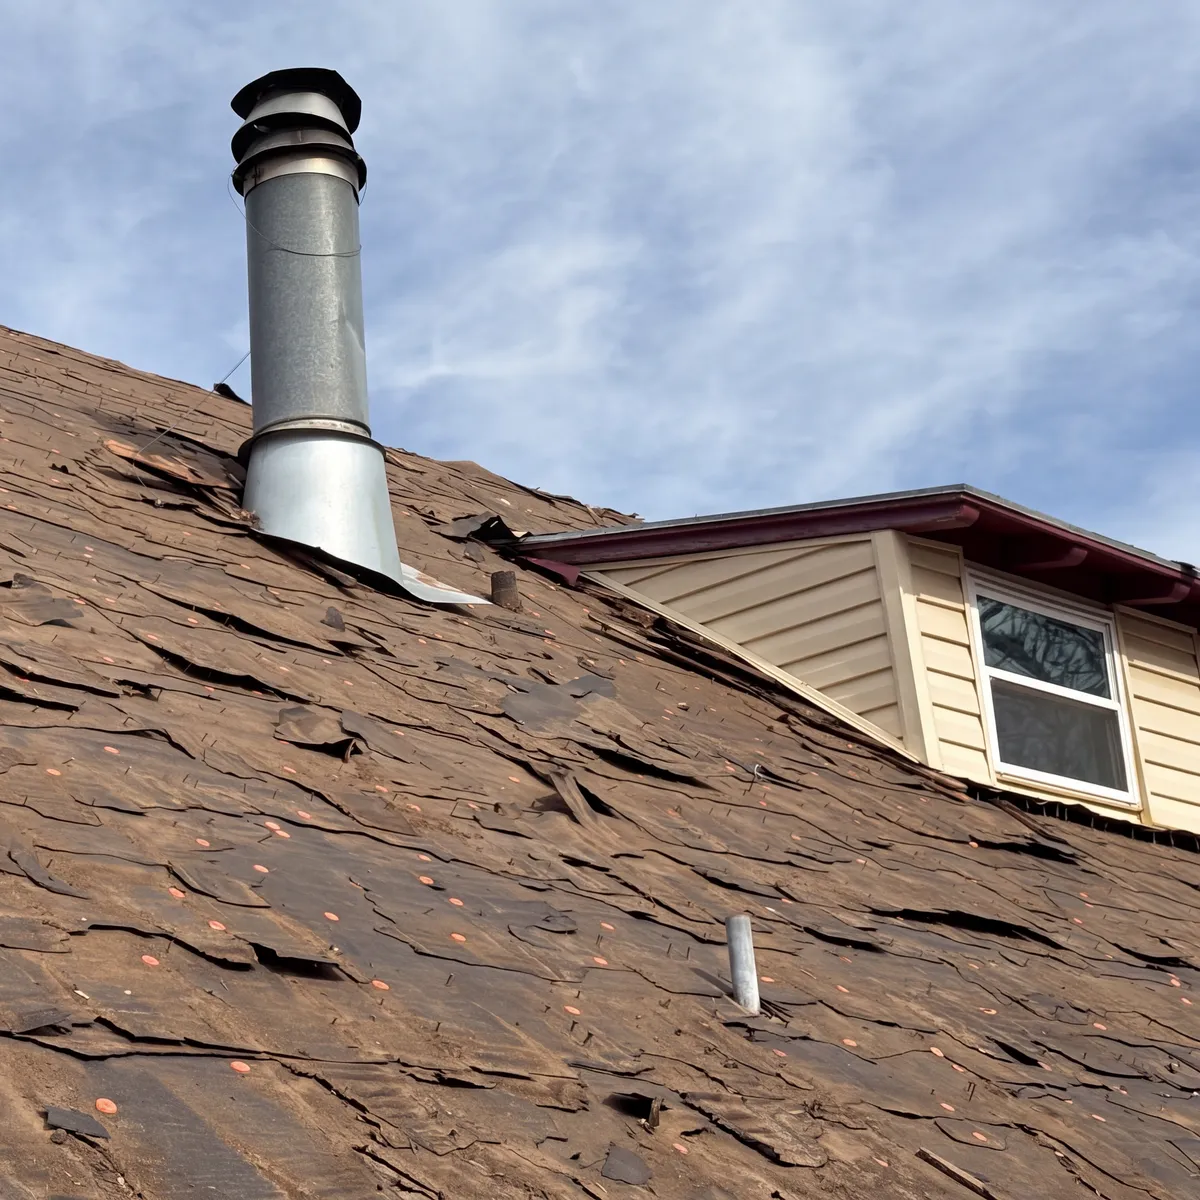
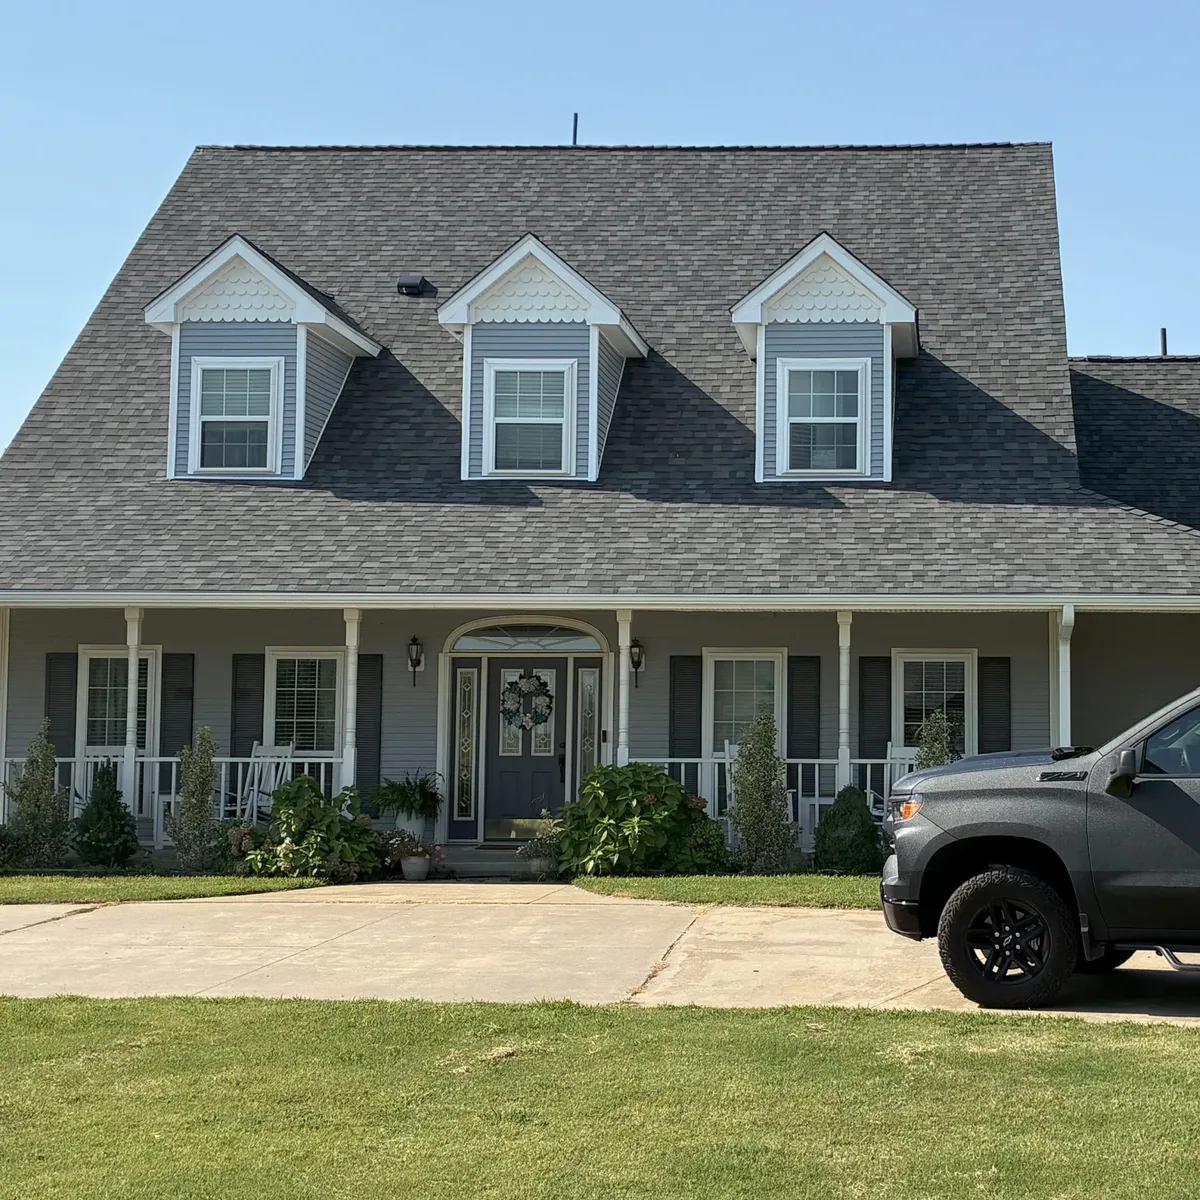
Real storm-related work completed in Oklahoma.
Storm work should be shown honestly. Not every project should be presented as a catastrophe.
Show what was found, what was approved, and what was completed.
What homeowners say about the process after a storm.
After a storm, homeowners remember more than the finished roof. They remember whether the company gave them a straight answer, kept them informed, respected their home, and followed through.
Questions About Storm & Hail Damage
How do I know whether hail damaged my roof?
A professional roof and exterior assessment is the safest way to evaluate the property. Possible context may include damaged roofing, exterior metals, gutters, siding, windows, screens, or nearby property. One dent or neighborhood report does not automatically prove that the roof requires replacement.
Can a roof have storm damage without leaking?
Yes. Some storm-related conditions may not create an immediate visible interior leak. The absence of a leak does not by itself confirm that the roof is undamaged.
Does a dented roof vent mean I need a new roof?
Not automatically. Dented metal can provide useful storm context, but the roof covering and complete system still need to be evaluated.
Should I file a claim before calling a roofer?
Not necessarily. Starting with a Free, No-Obligation Forensic Roof Assessment can help you understand the visible condition before deciding whether a claim deserves consideration. You decide whether to file. The carrier decides coverage.
Is the Forensic Roof Assessment free?
Yes. The assessment is free and comes with no obligation to hire 8:12 Roofing & Exteriors.
How long does the assessment take?
A typical assessment takes about one hour. The property's size, design, access, condition, areas being evaluated, and adjuster collaboration may affect the time.
Do I need to be home?
No. We coordinate timing, safe access, gates, pets, areas of concern, and special instructions before arriving. Homeowner presence may be helpful when interior access is needed.
Can 8:12 meet my insurance adjuster?
Yes, when scheduling allows. We often coordinate the assessment around the adjuster visit so visible roofing and exterior conditions can be reviewed at the property.
Does 8:12 negotiate with the insurance company?
No. 8:12 provides roofing and construction information, documentation, measurements, and scope details. We do not act as a public adjuster or negotiate the homeowner's insurance settlement.
Who decides whether the claim is covered?
The insurance carrier decides coverage according to the policy and claim investigation. 8:12 does not guarantee approval, payment, repair, or replacement.
What if the insurance estimate does not include all of the documented construction work?
8:12 may provide relevant construction documentation when the documented project needs differ from the carrier estimate. The carrier still decides coverage and payment.
Do I have to pay my deductible?
The deductible is the homeowner's responsibility under the policy. 8:12 does not waive, absorb, conceal, or misrepresent deductibles. Under Oklahoma House Bill 1940, it is illegal for roofing contractors to pay, waive, or cover any portion of a property insurance deductible.
What is the difference between ACV and RCV?
Actual Cash Value generally reflects depreciated value. Replacement Cost Value generally reflects the cost to repair or replace according to the policy's terms and limits. The actual policy controls how a specific claim is settled.
What is recoverable depreciation?
Some replacement-cost policies may initially withhold depreciation and release eligible amounts after covered work is completed and required documentation is supplied. Not every policy handles roof claims the same way.
Will insurance pay for an upgraded roof system?
Insurance coverage and carrier payment depend on the policy and claim decision. Homeowners may choose approved upgrades and pay any difference not covered by insurance.
Can storm damage be repaired instead of replaced?
Sometimes. A focused repair may be appropriate when the damage is isolated, compatible materials are available, and the surrounding roof remains serviceable.
Do you only work on insurance projects?
No. 8:12 works with homeowners using insurance, direct payment, financing, or another approved payment arrangement.
Is financing available?
Yes. Financing options may be available for qualified roofing and exterior projects. Approval, rates, and terms are determined by the lender. Financing does not replace the homeowner's insurance deductible.
What if no damage is found?
We will tell you. The goal is a straight answer, not a predetermined claim or sale.
What areas does 8:12 serve?
We serve Oklahoma City and surrounding metro communities, including Edmond, Norman, Moore, Yukon, Mustang, Midwest City, Del City, and many more. Click here to see our full service area.
What should I do when water is entering right now?
Keep people and pets away from unsafe ceilings and electrical areas. Do not climb onto the roof. Move belongings and collect water when it is safe, then call or text 8:12 and explain what is happening.
Before you file a claim, sign a contract, or assume the worst, get the full picture.
You do not need to diagnose the roof from the ground. You do not need to make a claim decision based on a door knock. And you should not commit to repair or replacement without understanding the evidence.
We will evaluate the visible roofing and exterior conditions, document what we find, and help you understand the reasonable next step.
Your peace of mind is our product. No pressure. No claim pitch. Just facts.
Oklahoma City-based. Veteran operated. Licensed and insured in Oklahoma.
Services
This is a Paragraph Font
This is a Paragraph Font
Company
This is a Paragraph Font
This is a Paragraph Font
Contact
101 Park Avenue, Suite 1300 (#13434), Oklahoma City, Oklahoma, 73102
CIB REG: 80007114


© 2026 8:12 Roofing & Exteriors. All rights reserved.
Oklahoma City-based. Veteran operated. Licensed and insured in Oklahoma.
Services
Company
Contact
101 Park Avenue, Suite 1300 (#13434), Oklahoma City, Oklahoma, 73102
CIB REG: 80007114
© 2026 8:12 Roofing & Exteriors. All rights reserved.